• Speck Hyundai of Tri-Cities

Blog / Automotive Financing

Leasing vs. Financing: Which Option is Right for You?

Business professionals shaking hands after successful meeting, showing agreement and partnership in office setting

If you're in the market for a new vehicle, one of the biggest decisions you'll face is whether to lease or finance your car. Both options have their benefits, and understanding the key differences can help you make the best choice for your budget and lifestyle. Let's break it down in simple terms.

What is Leasing?

Leasing a car is similar to renting. You get to drive a brand-new vehicle for a set period (usually two to three years) while making monthly payments. When the lease term ends, you return the car to the dealership, though in some cases, you have the option to buy it.

Pros of Leasing:

  • Lower Monthly Payments: Lease payments are often lower than loan payments because you're only paying for the car's depreciation during the lease term, not the full value.
  • New Car Every Few Years: Leasing allows you to upgrade to a new model every few years with the latest technology and safety features.
  • Lower Repair Costs: Most leased cars are under warranty for the duration of the lease, reducing unexpected repair expenses

Cons of Leasing:

  • Mileage Limits: Leases come with mileage restrictions, usually ranging from 10,000 to 15,000 miles per year. Exceeding this limit results in extra fees.
  • No Ownership: You don't build equity in the vehicle since you return it at the end of the lease.
  • Potential Fees: You may be charged for excessive wear and tear or early lease termination.

What is Financing?

Financing means taking out a loan to buy a car. You make monthly payments until the loan is paid off, and once it is, the car is yours to keep or sell.

Pros of Financing?

  • Ownership: When you finance a car, it's yours once the loan is paid off.
  • No Mileage Restrictions: Unlike leasing, you can drive as many miles as you want without worrying about extra fees.
  • Freedom to Customize: You can modify or personalize the car however you like.

Cons of Financing:

  • Higher Monthly Payments: Loan payments are generally higher than lease payments because you're paying off the entire value of the car.
  • Depreciation: The car loses value over time, and when you're ready to sell or trade it in, it may be worth much less than what you paid.
  • Out-of-Warranty Repairs: Once the warranty expires, repair costs come out of your pocket.

Final Thoughts

No matter which route you take, our dealership is here to help you explore your options and find the perfect vehicle for your needs. Visit us today to learn more!
Posted in:

Related Posts

itin financing

Can You Finance a Car With an ITIN? What Tri-Cities Drivers Should Know

If you are wondering whether you can get a car loan with an ITIN in the Tri-Cities, WA, the answer is yes. At Speck Hyundai, we offer ITIN auto financing for drivers across Kennewick, Richland, Pasco, and the entire Yakima Valley. You do not need a Social Security Number to finance a vehicle at Speck Hyundai. Here is everything Tri-Cities drivers need to know about ITIN car loans and auto financing in the Tri-Cities, WA. What Is an ITIN? An ITIN is an Individual Taxpayer Identification Number issued by the Internal Revenue Service. It is issued to individuals who need a U.S. taxpayer identification number but are not eligible for a Social Security Number. It is used exclusively for tax purposes but can also be used for ITIN auto financing in many situations. Can You Get a Car Loan With an ITIN? Yes. Many lenders accept an ITIN in place of a Social Security Number for car loan applications. At Speck Hyundai, our finance team works with a wide network of lenders who specialize in ITIN auto financing. That includes lenders who specifically serve Tri-Cities area buyers who use an ITIN. We help ITIN holders get approved for both new and used vehicle financing every single day. How Does ITIN Auto Financing Work? The ITIN auto financing process at Speck Hyundai works similarly to a traditional loan application. Here is what our lenders will typically review: Your ITIN number in place of a Social Security Number Proof of income including recent pay stubs or bank statements Proof of residence including a utility bill or lease agreement Down payment amount and trade-in information if applicable Any established credit history you may have built over time Employment history and length of time with your current employer What If I Have No Credit History? A car loan with an ITIN and no credit history is still possible at Speck Hyundai. Here is what can help strengthen your application: Larger Down Payment A larger down payment reduces the lender's risk significantly. Even a modest $1,000 to $2,000 down can make a meaningful difference in your application outcome. Proof of Stable Income Consistent and verifiable income is one of the strongest factors in any ITIN auto financing application. Bring recent pay stubs or bank statements showing regular income deposits when you visit. Co-Signer A co-signer with established U.S. credit can significantly improve your chances of approval. A trusted family member or friend with good credit can make a real difference. Longer Employment History Consistent employment with the same employer for six months or more is a strong positive signal to lenders. We Work With Local Credit Unions At Speck Hyundai, we have strong relationships with local credit unions and lenders across the Tri-Cities area. Many of these local lenders have experience working with ITIN holders and first-time buyers in our community. Our finance team shops your application across multiple lenders simultaneously to find the best available rate and terms for your situation. What Documents Do You Need? Bring the following when you visit Speck Hyundai: Your ITIN card or official IRS documentation Valid government-issued photo ID including passport or consular ID Proof of income including recent pay stubs or bank statements Proof of residence including a utility bill or lease agreement Down payment in the form of cash, check, or trade-in vehicle Proof of active auto insurance before finalizing your loan Our Bilingual Team Is Here to Help At Speck Hyundai, we have Spanish-speaking team members ready to assist you through every step of the ITIN auto financing process. Our bilingual team makes sure every Tri-Cities customer fully understands their car loan with an ITIN before signing anything. No pressure, no confusion, and no surprises. Come See Us at Speck Hyundai Ready to apply for ITIN auto financing in the Tri-Cities, WA? Bring your documents, come in with an open mind, and let us find the right vehicle and payment for you. We serve Kennewick, Richland, Pasco, and the entire Yakima Valley. Your path to reliable transportation with an ITIN car loan starts at Speck Hyundai today. Apply for Financing The information provided is for general informational purposes only and does not constitute legal, financial, or professional advice. While we strive to provide accurate and up-to-date information, we make no guarantees regarding the completeness, accuracy, or reliability of the information presented. Any action you take based on the context of this blog is strictly at your own risk. Always consult a qualified professional or specialist for advice specific to your situation. We are not responsible for any losses or damages arising from the use of this blog or its content

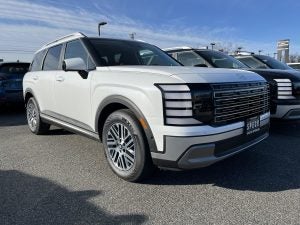
Image of a new 2026 Hyundai Palisade

What to Know Before Leasing a Vehicle

Leasing a vehicle is a great option for those who want lower monthly payments and the ability to drive a new car every few years. However, before signing a lease, it's important to understand the key aspects of leasing and how it differs from buying. Key Considerations Before Leasing 1. Lease Terms & Mileage Limits Most leases last 24 to 36 months. Leases typically come with annual mileage limits (10,000-15,000 miles per year). Exceeding the mileage limit can result in extra fees per mile 2. Monthly Payments & Costs Leasing usually has lower monthly payments than financing. Be prepared for down payments, acquisition fees, and , disposition fees. You're responsible for maintenance and excess wear-and-tear charges. 3. End-of-Lease Options Return the vehicle and lease a new one. Purchase the leased vehicle if you want to keep it. Extend your lease if you need more time. 4. Insurance Requirements Leased vehicles often require higher coverage limits. GAP insurance may be required to cover potential depreciation gaps. 5. Customization & Restrictions Modifications to leased vehicles are usually not allowed. You must return the vehicle in good condition to avoid extra fees. Final Thoughts Come on over to Speck Hyundai of Tri-Cities, a top Hyundai dealer, and check out our large selection of new Hyundai's available for lease. Be sure to ask if we have any specials or rebates available as well! Leasing can be a smart financial choice if you prefer lower payments and driving the latest models. Understanding the lease terms and potential costs will help you make an informed decision. Visit our dealership today to explore leasing options and find the perfect vehicle for you!

Image of a New 2026 Hyundai Santa Fe

What is Hyundai's New Car Warranty

One of the biggest advantages to consider while you are looking for a new Hyundai for sale is the brand's industry leading warranty coverage. Compared to the leading car manufactures, Hyundai is known for offering one of the most generous new vehicle warranties. You know that you can get long term peace of mind from day one. Hyundai's 10-Year / 10,000-Mile Powertrain Warranty Hyundai's leading coverage is its 10-year/100,000-mile powertrain limited warranty. The covers many major components including: Engine Transmission Transaxle Drivetrain systems This coverage excels in protecting against unexpected repair costs for some of the most expensive parts of your vehicle which is great for original owners. 5-year / 60,000-Mile New Vehicle Limited Warranty On top of the above warranty, new Hyundai's also come with a 5-year/60,000-mile bumper-to-bumper limited warranty. This covers the factory-installed components, offering elite coverage early into ownership. Additional Warranty Benefits Hyundai warranty also includes 7-year/unlimited-mile anti-perforation warranty (rust protection) 5-year/unlimited-mile roadside assistance Coverage for select emissions components These added benefits make the overall ownership of your new Hyundai experience stronger with the extra reassurance. Final Thoughts One of the strongest new car warranties in the automotive industry belongs to Hyundai. Including the long-term powertrain protection and great bumper-to-bumper coverage, you can count on that your new Hyundai is backed by confidence. Come visit us at Speck Hyundai of Tri-Cities, a top rated Hyundai dealer, and learn even more about Hyundai's new car warranty and more.